Many roof claims around St. Louis start the same way: a hail or wind storm, a few shingles in the yard or a dent in a gutter, and a call to the insurance company. What happens next follows a fairly predictable path, and Missouri has rules that protect you along the way.
This guide walks that path in order. It explains how claims usually work, not what your policy covers, so treat your policy and your agent as the final word.
- Photograph the damage, note the storm date and report the claim as soon as you know there is damage.
- Missouri regulations put insurers on the clock, starting with acknowledging your claim within 10 working days.
- Actual cash value subtracts depreciation. With replacement cost coverage, the held-back amount is usually paid after the work is done.
- Missouri law bars roofers from paying your deductible or negotiating your claim, and lets you cancel a roofing contract within five business days if your insurer says the work is not covered.
Step one: document the damage and the date
Before anything is repaired, take photos or video of every damaged area, inside and out, and write down what you see. The Missouri Department of Commerce and Insurance (DCI) recommends exactly that in its Post-Disaster Claims Guide. Photos of the house from before the storm help too, if you have them.
Pin down the storm date. NOAA's Storm Events Database holds National Weather Service storm records by county and date, though entries post a few months later: on October 2, 2026, it ran through June 2026. For the days right after a storm, the Storm Prediction Center posts preliminary hail and wind reports. Our after-the-storm checklist covers both in more detail.
If water is getting in, make temporary repairs such as a tarp and keep every receipt. DCI warns that further damage you could have prevented will likely not be covered, and that permanent repairs made before your insurer inspects could get the claim denied.
Step two: report the claim promptly
Call your agent or your insurer's claims line as soon as you know there is damage. DCI suggests asking for your claim number, the name of everyone you speak with, how long you have to file, whether you have a separate wind or hail deductible, and when to expect the adjuster.
Know your deductible before you call. If the damage looks minor, a repair might cost less than the deductible. DCI also notes that you might not be able to see all the damage, and suggests you may want a contractor to inspect the house.
Missouri regulations then set the pace for your insurer. Under 20 CSR 100-1.030, it must acknowledge your claim within 10 working days. Under 20 CSR 100-1.050, it must finish investigating within 30 days unless that cannot reasonably be done, and it must tell you whether it accepts or denies the claim within 15 working days after you submit the forms it needs.
A denial based on a policy provision has to be in writing and cite that provision. If the insurer needs more time, it must tell you why and send an update letter every 45 days. After big storms, adjusters can be stretched thin: DCI noted in June 2025 that some come from other states after major events and that waits can run longer, but your insurer should still be able to outline next steps.
Step three: the adjuster visit
Your insurer will send either a staff adjuster or an independent adjuster it hires. Either way, the insurer pays them, and DCI says you should not be asked for any payment. Ask to see identification.
Be home for the visit if you can. Show the adjuster every area of damage, and hand over your photos, notes and any written bids. Before the adjuster leaves, get their contact information and ask what happens next and when you will hear back. DCI's guide includes a claim log for keeping track of every call.
Step four: read the scope and the settlement
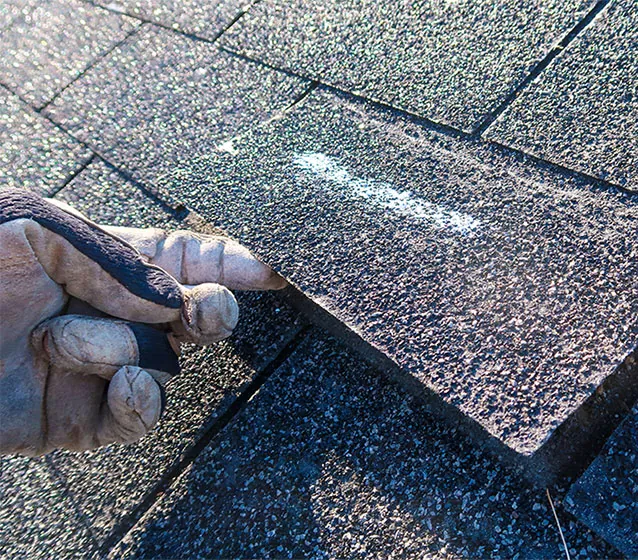
The adjuster's estimate is often called the scope. DCI describes the scope of loss as a detailed list of materials, quantities, labor, overhead and profit, code compliance and every item needed to repair or rebuild. On a roof, read it line by line: squares, tear-off, underlayment, drip edge, flashing, vents, ridge cap and any decking.
Actual cash value versus replacement cost. Replacement cost value (RCV) coverage pays to repair or replace without deducting depreciation. Actual cash value (ACV) coverage pays the depreciated amount.
DCI's example uses two identical $15,000 roofs, 10 years old, with $1,000 deductibles. The RCV policy pays $14,000. The ACV policy, depreciating the roof $1,000 a year, pays $4,000.
Recoverable depreciation. Many RCV policies pay the ACV amount first, then release the held-back depreciation once you show the work is done. DCI says the time limit to claim it typically runs six months to two years, depending on state law and your policy, so ask your adjuster for yours.
Roof-only rules. Even an RCV policy can treat the roof differently, and DCI notes some policies pay ACV on the roof and RCV on the rest of the house. Its roof coverage summaries for Missouri's 20 largest home insurers show several switching older roofs to ACV, at ages from 11 to 16 years depending on the company and roofing material.
Payments. Expect more than one check. If you have a mortgage, DCI explains, the lender is usually named on checks for major repairs, so you will need to work with them to release the money.
Deductibles, code upgrades and supplements
Your deductible is your share of the loss. It may be a flat amount or a percentage of your dwelling coverage, and in DCI's example a 2% deductible on a home insured for $250,000 is $5,000. Some policies have a separate wind and hail deductible, or one that applies only to the roof.
Code upgrades are a separate question. Standard homeowners policies do not pay the extra cost of meeting current building codes. Ordinance and law coverage does, up to its limit, so check your declarations page. For how these pieces add up on a whole roof, see our roof replacement cost guide.
Sometimes a crew finds damage nobody could see at the adjuster visit, such as soft decking under the old shingles. DCI's advice is to contact your insurer and adjuster any time you find damage that has not been reported or inspected. Send photos and a written estimate. In the trade, that added request is usually called a supplement.
What Missouri law says about roofing contracts tied to a claim
Section 407.725 of the Revised Statutes of Missouri, enacted in 2011 and amended in 2014, covers contractors who repair or replace roofs or do other exterior work. Under it:
- A contractor may not advertise or promise to pay or rebate any part of your insurance deductible. That includes allowances, discounts, gifts, prizes, bonuses, coupons, credits or referral fees.
- If your insurer notifies you in writing that all or part of the claim is not covered, you may cancel a contract to be paid by that insurance until midnight of the fifth business day after you receive the notice. Cancel in writing, to the address in the contract. A mailed notice counts once it is in the mail.
- Before you sign, the contractor must give you a boldface statement of that right and a "NOTICE OF CANCELLATION" form, in duplicate, attached to the contract.
- After a cancellation, the contractor has 10 days to return your payments and deposits, less the reasonable value of any emergency work you acknowledged in writing.
- A contractor may not represent you or negotiate for you on the insurance claim, or offer to.
- Violations count as unfair practices under the Missouri Merchandising Practices Act.
If you want someone to negotiate the claim for you, Missouri licenses public adjusters. DCI notes they take part of the settlement as their fee, that you do not need one to file a claim, and that it generally makes sense to consider one only after your insurer makes an offer.
Ask for any denial in writing and keep every document. If your policy has an appraisal clause, it sets out a process for disputes over the amount. DCI's consumer hotline, 800-726-7390, can help, and in October 2025 the department warned insurers against cancelling or non-renewing policies of homeowners still repairing damage from the spring 2025 storms. Be cautious with any document that assigns your insurance benefits to someone else.
How Correll helps with a storm claim
The claim stays yours. Missouri law does not let a roofer represent you or negotiate with your insurer, so our insurance claim help is the hands-on work around it, in this order:
- A free inspection of your roof and exterior, with photos and notes.
- A walk through what we found, photo by photo, before anything else happens.
- If there is storm damage worth claiming, help calling in your claim.
- A clear explanation of the next steps and timeline, and contact with you until the adjuster visit is scheduled.
- A meeting with your adjuster at the property. We arrive early and point out the damage we documented.
- A review of the adjuster's findings with you, and staying in touch with you until the claim is settled.
- A line-by-line look at the insurance scope with you. Then you sign the contract and pick any upgrades.
- Scheduling, staying involved through the install, and a final inspection with photos.
The inspection is free, with no obligation and no pressure. Read more about insurance claim help and storm damage repair, or schedule an inspection. If you are still choosing a contractor, our guide to choosing a roofer after a storm has a checklist.
- Post-Disaster Claims Guide (revised September 2023), Missouri Department of Commerce and Insurance
- Resources for Severe Weather Victims, Missouri Department of Commerce and Insurance
- DCI continues to provide consumer support and guidance following recent severe weather events (June 3, 2025), Missouri Department of Commerce and Insurance
- DCI issues stern warning on termination of coverage for storm-damaged homes (October 13, 2025), Missouri Department of Commerce and Insurance
- Raising the Roof on Insurance Coverage, Missouri Department of Commerce and Insurance
- Section 407.725, Work and services for insured persons, Missouri Revisor of Statutes
- 20 CSR 100-1, Improper or Unfair Claims Settlement Practices, Missouri Code of State Regulations
- Storm Events Database, NOAA National Centers for Environmental Information
- Storm Reports, NOAA Storm Prediction Center