Insurance claims
Storm damage and insurance claims, handled with you.
We help you through hail and wind claims: a free inspection, photos of the damage, a roofer at the adjuster visit and a line-by-line walk through the insurance scope. The claim stays yours.
Prefer to talk? Call (314) 222-9529
Dealing with your home insurance after a storm can be full of headaches. We make it easier: we document the damage with photos, help you start the claim, meet your adjuster at the house to point out what we found, and go over the insurance scope with you so you can see whether it covers what the storm actually did.
You stay in charge of the claim and every decision. Missouri law does not let roofers represent or negotiate for homeowners on insurance claims, and we follow it. Our job is to make sure the damage is documented and that you understand each step before it happens.
Before you call your insurer
- Write down the storm date and time
- Photograph damage from the ground
- Do not climb on the roof
- Book a free inspection before you file
The process
How a claim works with Correll
Eight steps, from the first look at your roof to the final walkthrough. We explain each one before it happens.
Start with a free inspection- 1
Free inspection
We go over the roof and exterior and photograph what we find: hail hits, wind damage, worn spots, gutters, vents and siding.
- 2
We show you the photos
Before anything else happens, we walk you through the findings, photo by photo, and tell you plainly whether a claim makes sense.
- 3
Starting the claim
If there is storm damage worth claiming, we help you call it in to your insurance company and explain what happens next.
- 4
Staying in touch
We follow up with you until the adjuster visit is on the calendar, so the claim does not stall.
- 5
Meeting the adjuster
We meet your adjuster at the property, arrive early, and point out the damage we documented.
- 6
Going over the scope
When the insurance scope comes back, we break it down line by line with you and stay in touch until the claim is settled.
- 7
Contract and choices
You sign only when the scope is clear. Then you pick shingle colors and any upgrades you want.
- 8
The build and final walkthrough
We schedule the work, stay on top of it through the install, clean up, and finish with a final inspection and photos.
Why the claim stays yours
Missouri’s statute on contractors and insurance claims, section 407.725 of the Revised Statutes, sets three rules every roofer in the state has to follow. We think they are good rules, and you should expect any contractor you talk to to follow them too.
- No paying or rebating your deductible. A contractor may not advertise or promise to cover any part of it, and that includes discounts, gifts, credits or referral fees. Your deductible is your share of the loss under your policy.
- A five business day way out. If you sign a contract to be paid through your insurance and your insurer then tells you in writing that all or part of the claim is not covered, you can cancel before midnight on the fifth business day after that notice. Payments come back within ten days, apart from emergency work you approved in writing.
- No representing you on the claim. A contractor may not represent you or negotiate with your insurer for you, or offer to. If you want someone to negotiate, Missouri licenses public adjusters, and attorneys can help too.
Three things to understand on your scope
The adjuster’s estimate, often called the scope, lists the materials, quantities and labor the insurer agrees to pay for. We go over it with you line by line. Three terms do most of the work in deciding what you are paid.
- Your deductible: a flat amount or a percentage of your dwelling coverage, and some policies have a separate wind and hail deductible.
- Replacement cost or actual cash value: replacement cost coverage pays to replace the roof without subtracting depreciation; actual cash value coverage pays the depreciated amount. Some policies treat older roofs differently from the rest of the house.
- Recoverable depreciation: many replacement cost policies pay the actual cash value first and release the held-back depreciation once the work is done. DCI says the time limit to claim it typically runs six months to two years, so ask your adjuster for yours.
If more damage turns up, or the claim stalls
Sometimes a tear-off uncovers damage nobody could see at the adjuster visit, such as soft decking. DCI’s advice is to tell your insurer and adjuster about any damage that has not been reported or inspected, with photos and a written estimate. We document what we find so you have both.
If a claim is denied or you disagree with the amount, ask for the decision in writing and keep every document. Many policies include an appraisal clause for disputes over the amount, and DCI’s consumer hotline at 800-726-7390 takes questions and complaints. Our Missouri roof insurance claim guide walks through the whole process in more detail.
Missouri law at a glance
- Roofers may not pay or rebate your deductible
- You can cancel within five business days of a written denial
- Roofers may not represent you or negotiate your claim
Questions about your policy?
The Missouri Department of Commerce and Insurance consumer hotline takes questions and complaints.
Fixed on the spot
I had a leak in my roof and called a couple different roofing companies to check it out. None of them could figure out where it was coming from, they just told me I’d need a whole new roof. Then I called Correll Roofing Company. Curtis came out…
Knowledgeable, polite, and responsive
I contacted Correll Roofing about some shingles that I lost off of my roof during this last round of high winds that we experienced. Jon responded to my inquiry quickly, came out to my home and replaced the missing shingles in a very timely manner.…
Reassured me and walked me through the process
I had the pleasure of working with Devin Stinson and am currently getting my roof replaced. I had waited almost too long to do it as I am a first time homeowner. The process was a little scary but Devin reassured me and walked me through the process…
FAQ
Insurance claim questions
General information, not legal or coverage advice. Your policy and your insurer have the final word.
Should I call my insurance company or a roofer first?
Many homeowners start with a free inspection so they know what they are dealing with before they call. Either way, report storm damage promptly: your policy sets the deadline, so read it or ask your agent.
Can Correll negotiate my claim for me?
No. Missouri law (RSMo 407.725) does not allow roofers to represent or negotiate for a homeowner on an insurance claim. What we do is document the damage, help you start the claim, meet your adjuster at the property and go over the scope with you, so you can make your own decisions with the facts in front of you.
Will you be there when the adjuster comes?
Yes. We meet your adjuster at the property, arrive early and point out the damage we documented. It helps to be home too, so you can hear the adjuster’s findings firsthand.
What if the scope misses something?
Tell your insurer and adjuster, with photos and a written estimate of the missed items. We go over the scope with you line by line and can show you where it does not match the damage we photographed.
Do I have to file a claim to get a roof from you?
No. You can hire us for a repair or a replacement and pay for it directly, with no claim involved. The inspection is free either way.
Guides
Know the process before the adjuster comes.
Missouri roof insurance claims
From the first photos to the final check, here is how a Missouri storm claim usually unfolds, what actual cash value and recoverable depreciation mean, and what state law says about roofing contracts.
Read the guide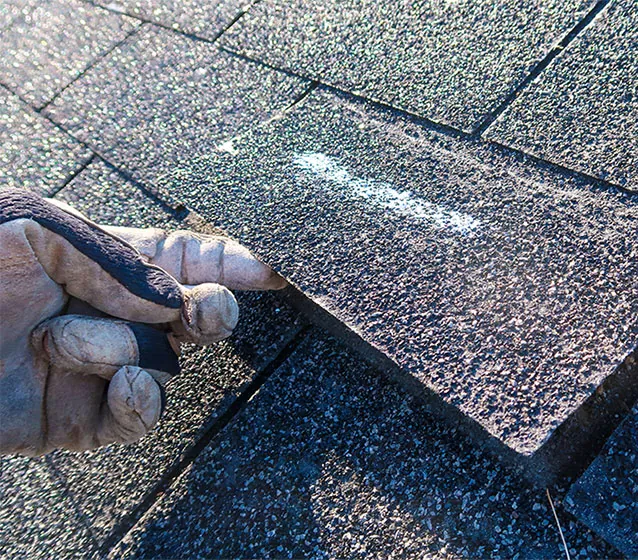
After a hail or wind storm
A calm checklist for the first two days after hail or high wind. Stay safe, check from the ground, document the storm date, protect the house, call your insurer and sign nothing at the door.
Read the guide
Choosing a roofer after a storm
After a big storm, the knocks on the door start fast. Here is how to check a roofer’s address, insurance and references, how deposits should work, and the Missouri rules that protect you.
Read the guide
Roofing With Integrity
Think the storm got your roof? Let’s look.
No obligation and no pressure. We look over the roof and exterior, photograph what we find and walk you through it. If you have storm damage, we help with the insurance claim from the first call.
- Call(314) 222-9529
- Emailoffice@correllroofingco.com
- Based in O’Fallon1048 Rondale Ct., O’Fallon, MO 63368
- Section 407.725, Work and services for insured persons, Missouri Revisor of Statutes
- Post-Disaster Claims Guide (revised September 2023), Missouri Department of Commerce and Insurance
- Resources for Severe Weather Victims, Missouri Department of Commerce and Insurance
- Raising the Roof on Insurance Coverage, Missouri Department of Commerce and Insurance